How Do Mortgage Advisers Balance Efficiency and Compliance?
For many mortgage advisers, the tension between efficiency and compliance is not theoretical. It shows up in everyday decisions. How quickly a case is progressed, how thoroughly information is recorded and how consistently processes are followed can all be affected by time pressure.
In practice, efficiency and compliance are not opposing goals. When they are aligned, they reinforce one another. The challenge lies in building a way of working that allows advisers to move through cases with clarity while maintaining the level of detail required to evidence suitability.
What Challenges Do Mortgage Advisers Face When Growing Their Business?
Growth is often seen as a positive step for mortgage advisers. More enquiries, a stronger pipeline and increasing case volumes can signal that a business is moving in the right direction. Over time, however, growth can introduce pressures that are less visible but equally important to manage.
As a business expands, the way it operates day to day begins to change. What once felt manageable can become more complex, particularly when balancing client expectations, regulatory requirements and the practical realities of running an advice business.
Understanding these challenges is an important part of managing growth in a way that remains controlled and sustainable.
How Do Mortgage Advisers Build a Sustainable Advice Business?
For many mortgage advisers, growth is often the focus. More clients, more cases and a stronger pipeline can feel like clear indicators of progress. Over time, however, it becomes apparent that growth alone is not enough to sustain a business.
Sustainability is built on something less visible. It sits in the consistency of decisions, the strength of processes and the ability to maintain standards regardless of workload or market conditions.
In a regulated environment, that balance becomes even more important. Advisers are not only managing client expectations, but also ensuring that every case can be clearly evidenced and is compliant.
What Does Good Record Keeping Look Like for Mortgage Advisers?
Record keeping sits at the centre of mortgage advice, even if it is not always the most visible part of the process. Every recommendation, every conversation and every decision needs to be supported by clear and accurate documentation. In a regulated environment, it is not enough for advice to be suitable. It must also be capable of being understood, evidenced and, if required, reviewed by a third party.
For mortgage advisers, strong record keeping is what connects the advice given to the rationale behind it.
How Do Mortgage Advisers Manage Regulatory Change in Practice?
Efficiency in a mortgage advice business is rarely about speed alone. It is more often the result of clear structure, organised workflows and the ability to manage each case in a consistent and controlled way.
Regulatory change is a constant in the mortgage market. New guidance is introduced, expectations evolve and existing rules are interpreted differently over time. For mortgage advisers, the challenge is not simply keeping pace, but applying those changes consistently
Managing that shift in practice requires more than awareness. It depends on having clear processes, reliable systems and a structured approach to reviewing how advice is delivered and evidenced.
What Systems and Processes Support an Efficient Mortgage Advice Business?
Efficiency in a mortgage advice business is rarely about speed alone. It is more often the result of clear structure, organised workflows and the ability to manage each case in a consistent and controlled way.
For mortgage advisers, the day-to-day reality involves balancing client communication, lender research, documentation and regulatory expectations. When those elements are not supported by the right systems and processes, even straightforward cases can become difficult to manage and harder to evidence. An efficient business is one where each stage of the advice journey is supported from initial enquiry through to completion, with systems and processes working together rather than in isolation.
How Do Mortgage Advisers Maintain Consistent Client Outcomes?
Consistency sits at the heart of good mortgage advice.
For mortgage advisers, consistent client outcomes are closely linked to suitability, documentation and the quality of the advice process. Clients expect clear, well‑reasoned recommendations that reflect their circumstances and objectives. Under Consumer Duty, firms must also be able to evidence that those outcomes are appropriate, fair and based on a thorough assessment of need.
How Does a Mortgage Network Support Regulatory Compliance?
For mortgage advisers, compliance is not simply a requirement. It is an ongoing responsibility that shapes how advice is delivered, documented and reviewed.
Within a network structure, regulatory accountability and oversight are organised differently to direct authorisation. Understanding how that framework operates is central to deciding whether the model is appropriate for your business.
Network or Direct Authorisation: Which Structure Is Right for a Mortgage Adviser?
Choosing how to structure your mortgage advice business is not a decision most advisers take lightly. Whether to become directly authorised or to operate as an appointed representative within a network affects accountability, infrastructure and the way compliance is managed day to day.
Both models sit within the same Financial Conduct Authority regulatory framework. The difference lies in where responsibility rests and how that responsibility is supported.
What Does Meaningful CPD Look Like for Mortgage Advisers?
At In Partnership, we view CPD as part of professional identity rather than administrative obligation. The way advisers engage with learning shapes the standards they maintain in practice.
What Does a Mortgage Adviser Network Provide?
Mortgage advisers in the UK can operate either as directly authorised firms or as appointed representatives within a network.
For many advisers, understanding what a mortgage adviser network provides is an important step in evaluating how best to structure their business.

In Partnership selects Comentis to better assess financial vulnerability
Meeting new Consumer Duty requirements
We raised £415 for dementia research
In Partnership took take part in March’s Make or Bake for dementia research

A massive farewell
This week marked the retirement of our long standing Senior Receptionist, Marguerite Tulley.
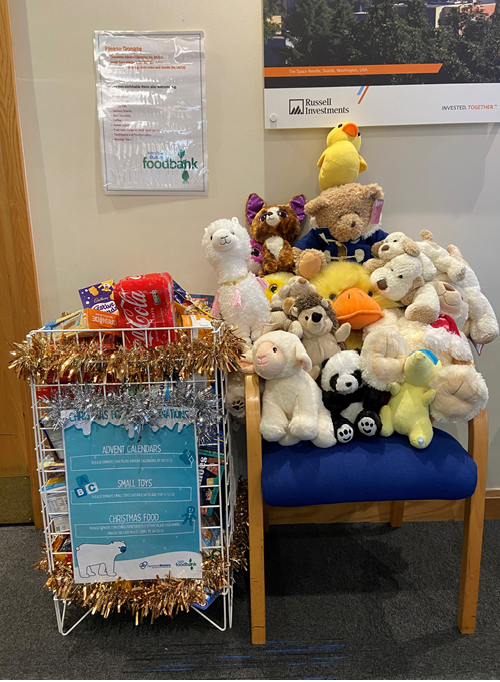
In Partnership supports Horsham Matters
We are proud to have supported Horsham Matters and help collect food and toys for those in need in the Horsham District